Tax Forms for New Employees: The Complete Checklist
Every tax form new employees need: W-4, I-9, state withholding, deadlines, penalties, and a step-by-step onboarding workflow for small businesses.
When I hired my first employee, I thought I had everything ready. Desk, laptop, a rough first-week plan. What I had not thought about was the compliance layer sitting underneath all of it.
A week later I was scrambling to figure out what a W-4 actually was, why the I-9 had a 3-business-day deadline I had already missed, and whether New York had its own withholding form on top of the federal one. It does. That scramble costs time, and it costs real money when penalties apply.
This guide covers every tax and compliance form a new employee needs to complete, the deadlines you cannot miss, and how to build the whole process into your onboarding workflow so nothing falls through the cracks. I built FirstHR partly because I got tired of managing this paperwork manually.
- Sign the offer letter
- Sign the employee handbook
- Workplace Safety course
What Tax Forms Do New Employees Need to Fill Out?
Two federal forms are legally required from every new employee. One state form is required in most states. One employer-side filing is required in all 50 states. Beyond those, a handful of administrative forms are standard practice even if not federally mandated.
The I-9 appears here even though it is technically an employment eligibility form, not a tax form. It earns its place because it is federally required for every hire, carries the highest penalty exposure of any new hire document, and is easy to complete incorrectly or late.
| Form | Who and when | What it is |
|---|---|---|
Form W-4 | Required by law · Employee completes · Day 1 or before | Federal income tax withholding certificate |
Form I-9 | Required by law · Employee + employer · Section 1 by Day 1 / Section 2 within 3 business days | Employment eligibility verification |
| Form | Who and when | What it is |
|---|---|---|
State withholding certificate | Required by law · Employee completes · Day 1 or before | Most income tax states publish their own form separate from the federal W-4 |
State new hire report | Required by law · Employer files · Within 20 days of hire, sooner in 9 jurisdictions | Employer files with a state agency. Required in every state and DC |
| Form | Who and when | What it is |
|---|---|---|
Direct deposit authorization | Employee completes · Day 1 | Employee bank routing and account number |
Employee handbook acknowledgment | Employee signs · Day 1 | Signed receipt confirming employee received company policies |
Benefits enrollment forms | Employee completes · Within 30 days (check plan deadlines) | Health, dental, and 401k elections |
Federal Tax Forms Every New Hire Must Complete
Two federal forms apply to every hire: Form W-4, which sets federal income tax withholding, and Form I-9, which confirms the employee is legally authorized to work in the United States.
Form W-4: Employee's Withholding Certificate
Form W-4 is the document every employee completes to tell you how much federal income tax to withhold from each paycheck. The current version replaced the old allowances system with a more direct dollar-amount approach tied to filing status, dependents, and other income sources.
Every new hire must complete a W-4 on or before Day 1. If an employee does not give you a properly completed one, the IRS tells you in Tax Topic 753 to withhold as if that person is single or married filing separately, with no other entries on Steps 2, 3, or 4.
There is no punitive default rate, whatever you may have read. The practical effect is still usually more tax withheld than the employee expected, which creates friction before the relationship has started.
The current W-4 has five steps. Steps 1 and 5 are required. Steps 2, 3, and 4 are optional and cover additional jobs, dependents, and other income adjustments. Most employees with a single job only need to complete the two required steps.


Form I-9: Employment Eligibility Verification
Form I-9 is required for every employee hired in the United States. It verifies that the employee is legally authorized to work. Every employer, regardless of size or how long they have been in business, must complete an I-9 for every hire.
The current Form I-9, edition 01/20/25, is built as two sections plus two supplements. Section 1 is completed by the employee on or before their first day of work. Section 2 is completed by the employer within 3 business days of the start date, after examining original identity and work authorization documents.
Supplement A covers a preparer or translator who helped the employee with Section 1. Supplement B handles reverification and rehire. Physical examination of the documents is the default, and physical means physical: not copies, not phone photos, not faxes.
The one exception is remote examination, and it is narrower than most owners assume. An employer enrolled in E-Verify and in good standing may use the Department of Homeland Security (DHS) alternative procedure: examine copies front and back, confirm over live video with the person holding the document, and keep clear copies on file. Everyone else examines in person.
For document retention, keep I-9s for 3 years after the hire date or 1 year after employment ends, whichever is later. Keeping them apart from other personnel files is a recommendation from U.S. Citizenship and Immigration Services (USCIS) rather than a legal duty, and it makes an inspection by U.S. Immigration and Customs Enforcement (ICE) faster to answer.
 Nick Anisimov, FirstHR founder
State Withholding Forms: What Most Income Tax States Require
Most states that tax wage income require their own withholding form on top of the federal W-4. States with no wage income tax require none.
Nine states levy no individual income tax on wages: Texas, Florida, Washington, Nevada, Wyoming, South Dakota, Alaska, Tennessee, and New Hampshire. If your business and your employee are both in one of them, the federal W-4 covers withholding and you need no state form.
Washington's Department of Revenue puts it plainly: the state does not currently have an individual income tax. It has legislated a 9.9% tax on adjusted gross income above $1 million, effective January 1, 2028, which is a filing question for high earners rather than a new hire paperwork question for you.
The other 41 states and the District of Columbia tax wage income, and most of them publish their own withholding certificate separate from the federal W-4. A handful accept the federal form as a substitute. The majority ask for their own document, with different fields, different exemption logic, and different instructions.
Using the federal W-4 in a state that wants its own form is a compliance gap. It shows up as incorrect withholding, which the employee discovers at tax time and the state discovers at audit.
| State | State Withholding Form | Notes |
|---|---|---|
| California | DE 4 | Required. Do not use federal W-4 for state withholding. |
| New York | IT-2104 | Required. Do not use federal W-4 for state withholding. |
| Illinois | IL-W-4 | Required. Do not use federal W-4 for state withholding. |
| Pennsylvania | REV-419 | Required for exemption claims only. |
| Massachusetts | M-4 | Required. Do not use federal W-4 for state withholding. |
| Michigan | MI-W4 | Required. Do not use federal W-4 for state withholding. |
| Georgia | G-4 | Required. Do not use federal W-4 for state withholding. |
| Virginia | VA-4 | Required. Do not use federal W-4 for state withholding. |
| Texas | None | No state income tax. Federal W-4 only. |
| Florida | None | No state income tax. Federal W-4 only. |
| Washington | None | No state income tax. Federal W-4 only. |
| Nevada | None | No state income tax. Federal W-4 only. |
California's Employment Development Department lists the DE 4 among its employer forms, and New York publishes IT-2104 with a new revision each year. Always pull the current version from the state agency itself before onboarding a new hire.
State forms get revised, and an outdated version creates problems during a state audit. California in particular has additional forms on top of the DE 4.
State New Hire Reporting
Separate from withholding forms, all 50 states and the District of Columbia require employers to report new hires to a state directory. The federal mandate sits in 42 U.S.C. 653a, enacted by the Personal Responsibility and Work Opportunity Reconciliation Act of 1996. States use the data to enforce child support obligations and detect unemployment fraud.
The federal outside limit is 20 days after the date of hire, and 9 jurisdictions run shorter than that: Alabama and Maine at 7 days, Georgia and Vermont at 10, Massachusetts, Rhode Island, and West Virginia at 14, and Iowa and Mississippi at 15. Work to your own state's number, not the federal ceiling.
The report typically includes the employee's name, address, Social Security number, and start date, plus the employer's name, address, and Federal Employer Identification Number. Most states have an online portal, and the Administration for Children and Families maintains the directory of them.
On penalties, the statute is narrower than the rumor. A state may charge up to $25 for each new hire reported late or not at all. The $500 figure people repeat applies only where the failure is the result of a conspiracy between employer and employee not to report, or to file a false or incomplete report.
Compliance Deadlines and Penalties You Cannot Afford to Miss
Three deadlines matter most: I-9 Section 1 on or before the first day of work, I-9 Section 2 within 3 business days, and the state new hire report within 20 days of hire, sooner in 9 jurisdictions.
The penalties for new hire tax form violations are specific, per-instance, and auditable years after the fact. Here is what the government charges:
| Violation | Penalty | Enforcement |
|---|---|---|
| I-9 paperwork violation, including a retention failure | $288 to $2,861 per individual | ICE / DHS audit |
| Knowingly employing an unauthorized worker (first order) | $716 to $5,724 per worker | ICE / DHS audit |
| Knowingly employing an unauthorized worker (third or later order) | $8,586 to $28,619 per worker | ICE / DHS audit |
| False W-4 statement by the employee | $500 civil penalty on the employee | IRS review |
| Unpaid trust fund taxes the employer withheld | 100% of the unpaid amount, assessed on responsible persons | IRS assessment |
| State new hire reporting failure | Up to $25 per late or missing report | State agency |
One row on that table is worth reading twice. The $500 penalty for a false withholding statement sits in 26 U.S.C. 6682 and lands on the employee, not on you. Your exposure runs the other way: it is the withheld tax you failed to deposit, not the W-4 the employee filled in badly.
How Tax Forms Fit Into Your Onboarding Workflow
Small businesses most often miss tax form deadlines because of timing, not ignorance. Forms get handed out on Day 1 in a stack, employees feel overwhelmed, something gets forgotten, and the 3-business-day I-9 clock runs out before anyone notices. The fix is integrating tax form collection into a structured timeline rather than treating it as a Day 1 task dump.
The most important shift in this timeline: move everything possible to preboarding. W-4, state withholding form, direct deposit, and handbook acknowledgment can all be sent digitally before the employee starts. When they arrive on Day 1, the only paperwork left is the I-9, and its document examination normally happens in person anyway. Everything else is already done.
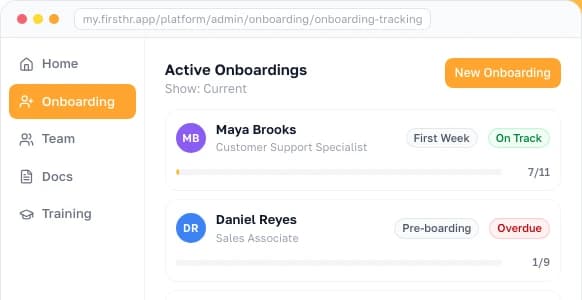
This is the workflow I built into FirstHR: an onboarding plan laid out in phases from preboarding onward, with each task carrying a due date and completion tracking so nothing gets missed.
Remote Employees and Multi-State Withholding
When an employee works remotely from a state different from where your business is located, you generally need to withhold income tax for the state where the employee works, not where your company is based. This creates withholding obligations in a state you may not yet be registered to do business in.
Practical example: your business is in Texas (no income tax), and you hire a remote employee who works from California. You now have California payroll tax obligations. You need to register as an employer in California, collect the DE 4 state withholding form from that employee, and remit California withholding on their behalf. The fact that your company is in Texas changes nothing from California's perspective.
A few states have reciprocity agreements. If your state and the employee's home state have a reciprocal agreement, the employee only pays income tax in one state (their state of residence). Always verify whether the two states have a reciprocity agreement before setting up withholding for remote hires across state lines.
Common Mistakes Small Businesses Make with New Hire Tax Forms
These are the six mistakes small businesses make most often with new hire tax forms.
The most expensive mistake on that list is letting employees start before I-9 Section 1 is complete. It happens when onboarding is rushed, when a hire is last-minute, or when an owner assumes the form can be backdated later. It cannot. Section 1 must be done on or before Day 1.
Build a hard stop into your process so Day 1 access is not granted until I-9 Section 1 is confirmed complete. Use the new hire checklist to confirm the new hire has the I-9 instructions and knows which documents to bring. That one step prevents the most common Day 1 I-9 delays.
Frequently Asked Questions
What tax forms do new employees need to fill out?
Every new employee must complete two federal forms: Form W-4 for federal income tax withholding and Form I-9 for employment eligibility. A state withholding certificate comes on top of those when the employee works in a state that publishes one. Nine states tax no wage income, so employees working there need no state certificate, while most of the other 41 states and DC have a form of their own. As the employer, you also owe a state new hire report, due within 20 days of the hire date under federal law and sooner in 9 jurisdictions. Direct deposit authorization and benefits enrollment are standard practice but not federally mandated.
Do new employees need to fill out a W-4?
Yes. Every new employee must complete IRS Form W-4 on or before their first day of work. The form tells you how much federal income tax to take out of each paycheck, using filing status, dependents, and other income instead of the old allowances. If no properly completed form arrives, IRS Tax Topic 753 has you treat the worker as single, or married filing separately, and leave Steps 2, 3, and 4 blank. In practice that usually means more tax withheld than the employee planned for, so it pays to chase the form during preboarding. Employees can submit a replacement W-4 whenever their tax situation changes.
What is the difference between a W-4 and a W-9?
A W-4 is the form your employees complete at hire to set federal income tax withholding, and you keep it in your records. A W-9 is for independent contractors and other non-employee payees, who complete it to give you their taxpayer identification number for 1099 reporting. Collecting a W-9 from someone who is really an employee is a serious mistake. It can trigger IRS scrutiny and liability for worker misclassification, which means treating an employee as a contractor. If someone is on your payroll and receives a regular paycheck, they need a W-4, not a W-9.
How long does an employer have to complete an I-9?
Section 2 of Form I-9 is due within 3 business days of the employee's first day of work, so a Monday start puts the deadline on Thursday. Section 1 is the employee's part, and it has to be finished no later than that first day. Where the job will last fewer than 3 business days, both sections are finished on the first day instead. Section 2 is where you examine original identity and work authorization documents, and physical examination is the default. Only an employer enrolled in E-Verify and in good standing may review copies over live video under the Department of Homeland Security (DHS) alternative procedure.
What state tax forms do new employees need?
It depends on where the employee works. Nine states charge no individual income tax on wages: Texas, Florida, Washington, Nevada, Wyoming, South Dakota, Alaska, Tennessee, and New Hampshire. For employees working there, the federal W-4 is the only withholding certificate you collect. In the other 41 states and the District of Columbia, wages are taxed, and most of those jurisdictions publish a certificate of their own to use alongside the federal form. California uses Form DE 4, New York uses IT-2104, and Illinois uses IL-W-4. A few of them accept the federal W-4 in its place, so ask the state revenue agency instead of guessing.
What happens if an employee does not fill out a W-4?
You still withhold. IRS Tax Topic 753 covers this case: an employee who never gives you a properly completed Form W-4 is treated as a single filer, or as married filing separately, with Steps 2, 3, and 4 left empty. Despite how often it gets repeated, no punitive top rate applies. Skipping withholding altogether is not an option, and the fallback treatment stays in place until a valid form arrives. You carry no penalty for the employee's failure to hand one in, so the practical fix is to collect the form early and let the employee's own choices replace the fallback.
What is state new hire reporting and is it required?
Yes, it is required everywhere. The requirement comes from 42 U.S.C. 653a, enacted by the Personal Responsibility and Work Opportunity Reconciliation Act of 1996, and it covers employers in all 50 states and the District of Columbia. Federal law gives you at most 20 days from the hire date to report, but 9 jurisdictions set a shorter clock: Alabama and Maine allow 7 days, Georgia and Vermont 10, Massachusetts, Rhode Island, and West Virginia 14, and Iowa and Mississippi 15. A report lists the worker's name, address, Social Security number, and start date, plus your own name, address, and Federal Employer Identification Number (FEIN). A late or missing report can draw a state fine of up to $25, and the $500 ceiling is reserved for an employer and employee who conspire to skip the report or to submit a false or incomplete one.
How long must employers keep new hire tax forms?
Keep each Form W-4 for at least 4 years and each Form I-9 for 3 years after the hire date or 1 year after employment ends, whichever is later. The IRS tells employers to hold completed W-4s in their own records and to send one in only if the IRS directs them to. State withholding certificates follow each state's own recordkeeping rules, so check with the state revenue agency rather than assuming the federal period carries over. U.S. Citizenship and Immigration Services (USCIS) recommends storing I-9s apart from general personnel files, though that is not a legal duty, and doing so keeps an auditor's reach narrow. Restricted access to all of it is sensible either way.
Make HR the easy part of running your business
Onboarding, e-signatures, training and core HR in one place. Up and running in 5 minutes.
- 7-day free trial
- No credit card required
- Cancel anytime